IMARC Group has recently released a new research study titled "Mexico Orthopedic Devices Market Size, Share, Trends and Forecast by Product Type, End User, and Region, 2026-2034", offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
Mexico Orthopedic Devices Market Size & Share 2026-2034
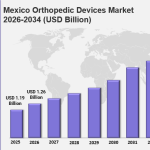
The Mexico orthopedic devices market size increased from USD 1.19 Billion in 2025 to USD 1.26 Billion in 2026 and is projected to reach USD 1.97 Billion by 2034, expanding at a CAGR of 5.76% during 2026-2034. In 2026, the market continues to gain momentum, driven by an aging population with a rising osteoarthritis and joint disease burden, expanding universal healthcare coverage, Mexico’s emergence as a medical tourism destination for cost-competitive joint replacement, and adoption of robotic-assisted surgery at premier private hospitals.
Joint replacement and orthopedic implants lead with a 43.8% share and hospitals account for 76.4% of end-user revenue, while Central Mexico leads with a 44.8% share (2025). The market is projected to reach USD 1.58 Billion by 2030, and these dynamics are expected to strengthen the Mexico orthopedic devices market share throughout the forecast period.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Market Size (2025): USD 1.19 Billion
- Market Size (2026): USD 1.26 Billion
- Projected Market Size (2034): USD 1.97 Billion
- Growth Rate: CAGR of 5.76% (2026-2034)
- Largest Region: Central Mexico (44.8% share, 2025)
- Fastest Growing Segment: Sports Medicine (~7.8% CAGR)
Explore Opportunities in the Mexico Orthopedic Devices Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-orthopedic-devices-market/requestsample
Key Growth Drivers and Trends in the Mexico Orthopedic Devices Market
Growth in the Mexico orthopedic devices market is being driven primarily by demographic aging and rising osteoarthritis prevalence. Mexico’s median age is projected to rise from around 30.5 years to 43 years by 2050, and combined with high obesity prevalence this is increasing the number of patients needing joint replacement. Expanding universal healthcare coverage is also improving access to orthopedic implants for previously uninsured populations.
One of the leading Mexico orthopedic devices market trends is the adoption of minimally invasive and advanced implant technologies. Other key trends include 3D-printed and patient-specific implants, advanced joint replacement implants with improved materials and durability, and next-generation cervical disc replacement technologies that preserve motion. Robotic-assisted surgery and digital surgical planning are also gaining ground at private hospitals.
Another key factor supporting Mexico orthopedic devices market growth is medical tourism and an active youth population. Cost advantages are drawing U.S. patients without insurance or with high-deductible plans to Mexico’s private hospitals, while the 41.0% of the population under 25 is generating growing demand for sports medicine and arthroscopic procedures such as ACL, meniscal, and rotator cuff repairs.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=43489&flag=C
Mexico Orthopedic Devices Industry Segmentation Insights
Breakup by Product Type:
- Joint Replacement/Orthopedic Implants: The largest product type with a 43.8% share in 2025, covering knee, hip, shoulder, and spinal implants, driven by osteoarthritis prevalence, an aging population, public health system prioritization of joint replacement, and the high value of implant systems.
- Trauma: Held 24.6% in 2025, covering intramedullary nails, bone plates and screws, and external fixation systems, and the highest-volume procedure category owing to road traffic accidents, occupational injuries, and falls among the elderly.
- Sports Medicine: Held 14.8% in 2025 and is the fastest-growing segment at ~7.8% CAGR, supported by ACL reconstruction, meniscal repair, and arthroscopic shoulder surgery.
- Orthobiologics: Held 10.2% in 2025, growing at ~7.2% CAGR through adoption of PRP, bone graft substitutes, and biologic augmentation.
- Others: Held 6.6% in 2025, including extremity implants and soft tissue repair.
Breakup by End User:
- Hospitals: The leading end user with a 76.4% share in 2025, owing to the surgical facilities, sterile field, anesthesia, imaging, and post-operative care that orthopedic implant procedures require; private hospital groups are the premium channel for robotics and advanced implants.
- Outpatient Facilities: Held 23.6% in 2025 and is growing at ~6.9% CAGR through ambulatory surgical center development for arthroscopic procedures, orthobiologic injections, and outpatient partial knee replacement.
Breakup by Region:
- Central Mexico: The largest region with a 44.8% share in 2025, supported by Mexico’s most sophisticated private hospitals, largest public hospital complexes, and highest density of board-certified orthopedic surgeons.
- Northern Mexico: Holds a 30.5% share in 2025, supported by a large industrial and maquiladora workforce with high musculoskeletal injury rates, developed private healthcare infrastructure, and cross-border medical tourism.
- Southern Mexico: Holds a 15.2% share in 2025, served mainly by regional trauma and basic joint replacement programs, with emerging medical tourism developments.
- Others: Holds a 9.5% share in 2025, comprising developing secondary markets with growing private hospital sectors and cross-border orthopedic medical tourism.
Key Challenges and Growth Opportunities in the Mexico Orthopedic Devices Market
The Mexico orthopedic devices market faces challenges including lengthy regulatory approval timelines that delay entry of advanced devices, and price sensitivity in public procurement that pressures margins and slows adoption of premium implants. Counterfeit and substandard implants in secondary channels, particularly trauma fixation devices, and limited surgeon training capacity for robotic joint replacement, minimally invasive spine surgery, and complex revision arthroplasty also constrain growth.
Despite these challenges, the market offers considerable growth opportunities, including robotic-assisted orthopedic surgery at private hospitals, where adoption is still at an early stage, and ambulatory surgical centers enabling same-day outpatient joint replacement. Medical tourism infrastructure, orthobiologics, cervical disc arthroplasty, and total ankle replacement are further identified as high-return opportunities through 2034.
Competitive Landscape
The Mexico orthopedic devices market is highly concentrated at the top. Stryker, Zimmer Biomet, Johnson & Johnson, Smith+Nephew, and Medtronic collectively account for an estimated 65-75% of organized market revenue, benefiting from established device registrations, public tender positions, and long-standing private hospital presence. Stryker, Zimmer Biomet, and Johnson & Johnson are positioned as market leaders, while Smith+Nephew and Medtronic are established players. Competition centers on public tender pricing, private hospital robotic system placements, and surgeon education programs. The IMARC report covers market structure, key player positioning, and detailed profiles of all major companies, including Stryker, Zimmer Biomet, Johnson & Johnson, Smith+Nephew, and Medtronic.
Recent Developments in the Mexico Orthopedic Devices Market
- August 2025: CG MedTech launched its UniSpace Stand-Alone C Cage in Mexico, a cervical fusion device that removes the need for additional plates, supporting smaller incisions and faster recovery.
- March 2024: NGMedical GmbH completed the first implantation of its MOVE-C cervical artificial disc in Mexico, featuring additively manufactured titanium endplates and multidirectional physiological motion.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302